Spreadsheets vs. Databases: How to weigh the Tech Benefits
- Jamie Black
- Tech for Execs
- minute(s)No doubt you have read many articles decrying the use of spreadsheets due to the myriad of disasters that have resulted from their use. We have a long history of ranting about their weaknesses when it comes to complex reporting tasks like generating a set of financial statements/Comprehensive Annual Financial Report. We have even written articles about how to avoid these mistakes, and about how to determine (calculate) if a spreadsheet is the right tool for a given task. What we have never done is present the technical reasons that spreadsheets are ill-suited for the job and why database-driven applications are far superior. That is what we will do in this article. Before we dive in, we should state a couple of items (before the hate mail comes pouring in): There are many spreadsheet applications & database-driven tools. Clearly, we cannot discuss each one and their differences in detail. Instead, we will speak generally about typical, common features found in products like Microsoft Excel/Google Sheets and Microsoft SQL Server. Spreadsheet applications have gotten increasingly sophisticated, have remained inexpensive and easy to use, which has naturally lead to their use for more complex tasks. If left to choose between using a spreadsheet or paper & pen, we would recommend the spreadsheet. Some of the problems people have with spreadsheets occur because they fail to follow best practices. Thus, some of the highly publicized disasters reflect a skill/experience problem, not a software problem. We are active proponents that just because you CAN use a tool for a task, does not mean that it is the BEST tool for the job. Similarities Spreadsheets provide a rapid, powerful, generic way to manipulate numbers in any form or fashion your heart desires. The intersection of columns and rows allows you to enter data or formulas to generate a wide range of results. A database-driven application extends the concept of a spreadsheet. A very rough comparison is that each “tab” in a spreadsheet workbook is equivalent to a database table, with each table consisting of rows and columns. A database is a collection of these tables and other metadata, just like a spreadsheet is a compilation of sheets. To be clear, we are using the term database here as it is the common expression. Differences Spreadsheet Database Driven Application Data (Transactions) User(s) performs data entry on the same spreadsheet that houses all the data. Two major approaches, both of which prevent the user from directly affecting previously recorded data: The user completes a Form & the system validates the data and if acceptable, adds it to the appropriate Table(s). The user imports large volumes of data. This data is validated to ensure acceptability, and it is added to appropriate Table(s). Calculation(s) User(s) adds calculations/formulas to Cells that reside with the raw data. Calculations are performed as needed, either on a Report or Form. Formatting Like calculations, formatting is usually applied by the user to a selection of Cells. Formatting is applied to the Report that pulls data from one or more Tables. Validation When used (infrequently in our experience) user(s) adds to a selection of Cells. Applied centrally to all actions involving data (importing, deleting, adding new records, etc.). Data Integrity No certainty that data added was added correctly & completely. Generally speaking, considerable technology is dedicated to ensuring integrity. For more details see this article on ACID. Scalability Has improved over time but is not designed to handle massive volumes of data. Depending on the particular database technology selected, capable of handling millions of records. Audit/Logging Some support with major gaps. Secure logging of essentially any & every item determined valuable is possible. Security Can be set at the Cell level but roles & groups are not supported. Extensive ability to assign roles & groups and specify permissions at any level. Spreadsheet weaknesses The argument for continuing to use spreadsheets is obvious - they are inexpensive and easy to use at a basic level. The problem with them is considerable however and can be seen in a common theme running through the comparison above. The major technological problem with the spreadsheet is the collapse of many elements into one sheet or even down into one cell. In a spreadsheet, the "data table" IS the report. Entering new "transactions" means being able to edit existing rows. This makes the large, complex spreadsheet very fragile. Make a mistake entering a formula and everything breaks. It is like a tower of Jenga blocks waiting to fall. Some of you may be typing a furious email to me right now saying "You can solve these issues in a spreadsheet. Just design it like a database and use all of its features, like macros." It is true, some of these issues can be handled IF you design your spreadsheet correctly and have extensive IT and programming skills; essentially, if you build an application inside your spreadsheet. Thus the argument for continuing use of spreadsheets for complex tasks is not compelling for 3 reasons: Untrained operators - It is great to say "develop the spreadsheet properly" but consider the typical spreadsheet developer. They are often accountants/finance professionals. Because anyone can use spreadsheets & they are so easy, people with no particular development training build incredibly complex documents. Consequently, these documents rarely conform to the best practices that an experienced developer would insist upon. In general, errors seem to occur in a few percent of all [spreadsheet] cells, ...In programming, we have learned to follow strict development disciplines to eliminate most errors. Surveys of spreadsheet developers indicate that spreadsheet creation, in contrast, is informal, and few organizations have comprehensive policies for spreadsheet development. Ray Panko - What We Know About Spreadsheet Errors Too little control - Spreadsheet tools are just not designed to enforce or in some cases even support best practices. One example of this is that many elements are combined/mixed together within each spreadsheet, sometimes even within one cell. Recall, spreadsheets are a generic tool designed to fit as many use-cases as possible. Thus, the user must: Know they need a given feature (like validation), Have the skills (which might include programming) to build it, Spend the time to build it, Technical Inability - Even if you have tremendous IT skills some actions are very difficult bordering on impossible within a spreadsheet: Managing large data sets - if you need to deal with millions of records, spreadsheets can not help you. Logging - It can be very difficult to determine which user added row 7 in our example. Or if you are dealing with thousands of rows, which rows were added and when? Documentation - if the person who created the spreadsheet leaves the organization, who else in the organization will know how to use what is essentially a custom application? There is no easy way to direct subsequent users where to start etc. other than some notes that you hope are updated and then followed by subsequent users. Database weaknesses All the power, validation and speed of a database driven solution comes at a cost. Depending on the exact database selected, the costs can be significantly higher than a spreadsheet and specialized hardware may be required. Further installing, configuring and maintaining a database takes specialized knowledge. Finally, one of the benefits of the database-driven application is one of the challenges- it constrains the user. In contrast to the Jenga metaphor of the spreadsheet, the database application can be thought of like a Rubiks Cube. The user can only do certain things in certain ways. Unlike the spreadsheet, there are rules about how the system can be used. The Bottom Line We have previously developed a detailed calculation to determine exactly when to use a spreadsheet but if you want to keep it simple, here is the cheat sheet for choosing between the two tools: Choose a spreadsheet (and follow best practices in how you build and use it) if the task is: simple, only used by one or two people, using a small set of data which will only be used once. Invest in a database driven application if the task is: complex, used by multiple people, standardized, may house a moderate to large data set and reoccurs. © 2025 FH Black Inc. All rights reserved. Content may not be reproduced, excerpted, distributed, or transmitted without prior written consent.
When & why should you upgrade from a spreadsheet to a database-driven application? The technological differences are significant & shouldn't be overlooked.
READ MORE
Is your finance department prepared for these 5 colossal changes?
- Jamie Black
- Finance Evolved
- minute(s)Perhaps the biggest failure of corporate governance today is its emphasis on short-term performance. Corporate Governance 2.0 - Harvard Business Review You may not realize it yet, but your organization is in the early stages of being hit by massive, interconnected and occasionally opposing global changes. These changes are likely not going to reach full strength for 10 or 20 years. None the less, it will take time, planning, and some hard work to get prepared. If these changes turn out to be as big as predicted, being ready may mean the difference between an organization that prospers and one that perishes. In our blog series "Finance Evolved", we consider major trends & forces and how they may affect the finance department to aid in your planning & preparation. Here are the big 5 looming trends: 1) Demographics The population of North America is aging in a way not seen before. This will cause havoc for businesses, governments and the economy generally. 2) Skills Recent surveys reveal gaps between the finance skills required by organizations and those possessed by entry-level management accounting and finance professionals. As the pace of change increases, the successful individual finance professional and the successful finance department will need perpetual skills development. 3) Productivity Despite technological improvements, the pace of growth in productivity has been slowing globally since the 90s. This has already impacted wages and may contribute to income/wealth inequalities and job insecurity in the future. 4) Budgets We see increasing levels of pressure for finance to accomplish more, faster with stagnant or decreasing budgets. Given the other big forces in this list, there is every reason to believe that this pressure will intensify. 5) Technology To say we are living in a time of rapid, continuous technological change is a cliche. There are signs that while the current rate of technological improvement may be slowing, the effects may well be poised to more dramatically affect the finance department than ever before. Be ready for the future Train & mentor staff - The difficulty you have today finding qualified, appropriately skilled staff is going to become much worse. Your best bet is to retain and develop your current team. Document & standardize - Expect the loss of a significant percentage of your most experienced, knowledgeable workforce in the next 2 decades. Without excellent organizational supports, this will come with a consequent decline in organizational productivity. Plan ahead - Governments at all levels will see reduced revenue growth and increased expenses, further straining budgets. You can expect reduced governmental services and/or increased taxation. Streamline & automate - Organizations of all types will be under growing pressure to increase productivity. Software and automated systems are your best tool to do more with less. Upgrade your skills - The requirement for greater productivity will mean that your value will be increasingly tied to your ability to lead, to streamline, to automate and to improve. Conversely, if your skills are primarily data entry/bookkeeping, you are likely to be automated into the unemployment line. Do you have the skills to leverage technology to help you address the dramatic staffing, efficiency, and budget challenges we will see in the next 10 to 20 years? Watch for future articles in our Finance Evolved series which will dive deeper into these topics and explore additional strategies designed to aid the transition to world-class finance organization. © 2025 FH Black Inc. All rights reserved. Content may not be reproduced, excerpted, distributed, or transmitted without prior written consent.
To function effectively & efficiently in the coming decades, your finance department must plan for these 5 major changes right now.
READ MORE
How to prepare a better solution requirement list for IT project ...
- Jamie Black
- Efficient, Effective and Reliable
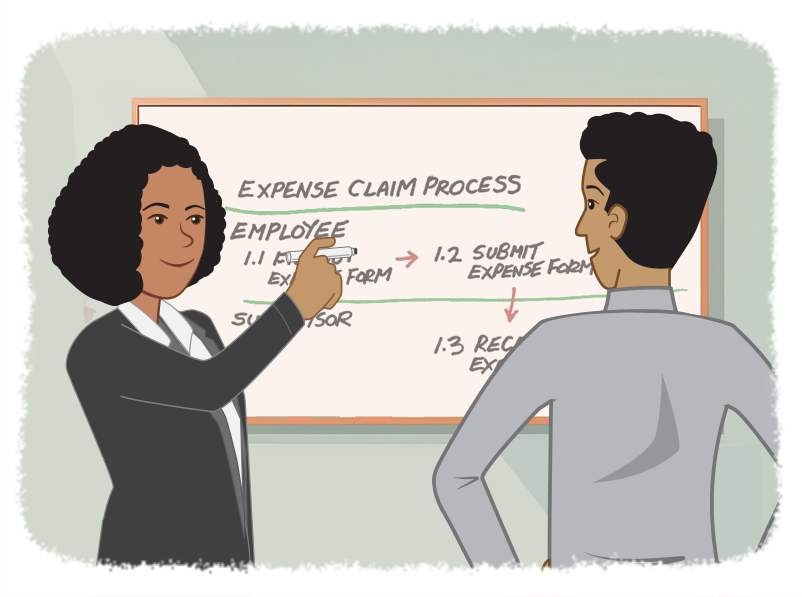
- minute(s)Many of our articles address factors related to IT project success and the significant rate at which these projects fail. There are many causes for failure; first among them is choosing a solution that does not meet the needs of your organization. Typically, selecting an IT solution begins with the Request For Proposal (RFP) process. The process seems logical—state your needs and ask vendors to supply a price to meet those needs. If you're buying a commodity with little differentiation among options, developing a list of requirements is important. But if you're buying an intangible like an IT solution, with unlimited variables and options, that list becomes absolutely critical. Unfortunately, it is very common to see software requirement lists for Annual Comprehensive Financial Report automation or Continuous Controls Monitoring (CCM) systems with requirements: That are very broad Derived exclusively from a vendor's list of features Copied from another, theoretically similar organization's RFP To see the error in this approach, imagine buying an expensive suit. After noticing it hanging in the store and being impressed with what you see, the next step is always to try it on. Why? It is the only way to guarantee it fits you. Even though the tag says it's your size, that is no guarantee of fit, is it? Take that suit home without trying it on and it might fit exactly (unlikely); it might need some alterations, or it might be completely wrong for your body. Why do so many organizations have such ill-defined requirements? The most common reasons include: The team disagrees that implementing a new IT system is like buying a suit; they see it as more like the purchase of socks—one size fits all. The team did not have time to formally document their needs, but felt that a good compromise was to use someone else's. The team did not have a clear idea of how to document their needs, so they chose to leverage those published by vendors or peers. How to document your needs If you fall into the third category above, you can improve the probability of your IT solution's success by applying these seven steps: Document your current business processes. Start by writing down each step. Visit the people who perform each step and ask them what they do, in what order, and why. Be prepared for some surprises. There will be steps you did not know about and shortcuts you never imagined. The benefits of this documentation process can go beyond selecting the right new system. For example, it can be the critical first step to updating your internal controls risk assessments or training materials. Prepare process diagrams. There are many ways to create this material, but we firmly recommend modeling your business process graphically. Business process diagrams (or models) are excellent at displaying process gaps or errors in understanding in a way that descriptions like those gathered in Step 1 will not. We recommend swimlane diagrams like this: Many applications can be used to create these diagrams. The most commonly used is Microsoft Visio but we also like Lucid Chart and Creately. Gather copies of any inputs (forms, authorizations, etc.) or outputs (reports) of your business processes as attachments to your documentation. Be sure to label the diagram to show where in the process they apply. Consider what could/should be improved: What is difficult today? Which steps in the current process take a long time? What would the value to the organization be if you could eliminate or shorten this time? Are all steps necessary? Could we remove any steps and still achieve our desired results? Often these opportunities will jump out at you in the diagram. They may appear as many steps that loop back on top of themselves, for example. Create new diagrams of the optimal future process, incorporating the items identified in Step 4. This improved process is a better representation of what you want your new system to support. Transform the new business process steps into a requirements list. For example, if a step in your diagram is, "Batch email statement," the requirement might be, "Ability to email statements to all accounts that have an outstanding balance without any manual intervention." Finally, now is the time to consider vendor feature lists or the needs documented in other, similar organizations to see if there are any items you may have overlooked. By applying these seven steps, you can tailor your software requirements list to your organization, and more likely find the solution that provides the greatest value. © 2025 FH Black Inc. All rights reserved. Content may not be reproduced, excerpted, distributed, or transmitted without prior written consent.
Follow these 7 steps when preparing a technology requirement list to ensure your next solution meets your needs.
READ MORE
Improve your Internal Controls to Lower Audit Fees
- Jamie Black
- In Control
- minute(s)If you're a typical finance department, discussions about Internal Controls are probably not part of your daily work day. In our experience, accounting teams start thinking and discussing Internal Control when they have: found an alarming incidence of error in their business processes are subjected to a performance audit (if they are a local government) heard of another organization falling victim to fraud Outside of these scenarios, the strength of internal controls systems doesn't often get a lot of finance's attention while they take care of payroll, budgeting, management reporting, financial reporting and so much more. There is a large, but often overlooked reason to focus on your internal controls system, an opportunity to reduce audit fees. Audit Fees Increase with Poor Internal Controls Poor internal controls and/or poor documentation of existing controls directly lead to increased audit fees. Why? Auditors must increase the amount of testing performed (sample size) when they determine that internal controls can not be relied upon (International Standard on Auditing - 530 Audit Sampling) to reduce audit risk to an acceptable level (International Standard on Auditing - 330 Auditor Responses to Assessed Risk). Specifically: "Deficiencies in the control environment, however, have the opposite effect; for example, the auditor may respond to an ineffective control environment by: • Conducting more audit procedures as of the period end rather than at an interim date. • Obtaining more extensive audit evidence from substantive procedures. • Increasing the number of locations to be included in the audit scope. The evidence of this direct relationship between audit fees and internal controls abounds. In December 2016, the Financial Executives Research Foundation (FERF) survey of more than 6,000 organizations found that reviews of internal controls continue to be one of the three major driving factors behind rising audit fees: More than 20% of the respondents that had audit fee increases cited a “review of manual controls from [Public Company Accounting Oversight Board] inspections.” Companies that cited ineffective internal controls as adding to audit fees experienced a 5.1% median increase, almost two percentage points higher than the median increase for all other filers. 3 Recommendations to Reduce Audit Fees In their follow up article "Mitigating Increases in Audit Fees" the FERF interviewed preparers and auditors to understand causes and develop recommendations. Several recommendations focused specifically on Internal Controls improvements that drive lower audit fees including: Align key controls with key risks: Ensuring the organization has strong controls to address the most significant risks will give management and auditors increased confidence. Document internal controls: If an organization has very light or poorly organized documentation, or hasn’t thought through all the branches in a process, attestation becomes difficult for the auditor — and more costly for you. Evaluate the latest technology: External and internal auditors are both using data analytics and continuous controls monitoring technology to increase audit quality, work smarter and potentially reduce costs. There are many great reasons to focus on improving your organizations' internal controls. Lower Audit fees is another good one. © 2025 FH Black Inc. All rights reserved. Content may not be reproduced, excerpted, distributed, or transmitted without prior written consent.
Finance professionals know the importance of strong internal controls for managing but overlook the opportunity to reduce audit fees.
READ MORE
7 Steps to Avoiding the Cheap IT Solution Selection Trap
- Jamie Black
- Efficient, Effective and Reliable
- minute(s)According to information technology research firm Gartner, 50–75 percent of IT projects fail. We've written a number of articles offering guidance for achieving better outcomes through the solution selection and implementation processes, but there is one trap we haven't addressed—and we see clients succumb to it all the time. Price Clouds Everything Consider the Canadian government's Phoenix payroll software debacle. They elected to have a payroll system custom developed by IBM, and have had nothing but problems with it. According to one assessment: "... the Harper government put so much emphasis on saving money that it undermined efforts to ensure that the system would function well...instead of saving the government 70 million Canadian dollars this year, as promised, Phoenix has cost the government an extra $50 million (about USD $37 million), including $6 million in additional fees paid to IBM to fix it." When participating in an IT system evaluation, if you find your team leaning toward the low-cost choice instead of the high-value solution, beware. No one wants to pay more for something than they need to. In government in particular, you may even have the obligation to choose the low-cost solution. This default preference/requirement is understood by IT solutions sales representatives and is often relied upon to accelerate the sales cycle and "close the deal." Even if you're not being exploited by sales teams, the Phoenix case shows how this low-cost bias can lead to dysfunction. Here are two questions to ask yourself to avoid a bad deal when considering the "cheap" IT solution: 1) Is it truly cheaper? In one respect, it is obvious; if the number at the bottom of the RFP response or quote is lower, then it's the less expensive option. While technically true, that is only a valuable assessment if you are comparing apples to apples. Before you look at the price, you need to know whether you'd be getting the same thing for the money. With an intangible product like software, it can be difficult to ensure you're making an apples-to-apples comparison. If you bought the Chevette above based solely on the price, you could be stuck with the wrong car if acceleration and top speed are necessary features. Alternatively, you might decide you do not need a Corvette, that a Chevette will do. The point is, they have different features and capabilities, and comparing the two options based solely on price obscures those differences. RECOMMENDATION: Before assessing products, explicitly and formally define your needs/requirements and evaluate your choices based on fit first. Don't allow the price to hijack the process. Use ROI instead of price to select among solutions that fit some/all of your requirements. 2) Why is it cheaper? There's no such thing as a free lunch. - Milton Friedman You've assessed the options based on fit. Then you calculated ROI. The cheaper solution comes out on top. What now? RECOMMENDATION: Treat the low-cost solution with extreme suspicion. This is your warning sign to bolster your due diligence. We recently watched one "low-cost" vendor in the reporting automation industry cease operations and advise their existing clients that they are on their own. For some of these folks, this happened while they were implementing the software. The Action Plan: 7 Steps to Better Due Diligence Double-check fit-assessment. If you have any doubt, have the low-cost vendors re-demo the product to confirm it meets your needs. Double-check standard pricing variables: Modules/features Number of users Number of people being trained Duration and extent of support period These are all variables that might account for significantly reduced cost. Remember, you want to compare apples to apples. Also, recall that skimping here may cause cost overruns later when you determine you did need more training or support. Assess the vendor track record. How many clients do they have? How many times have they solved the problem(s) you have? Ask about failed implementations and what caused them to fail. Be suspicious of anyone who says they don't have any. Closely assess their implementation team. Does the vendor have in-depth knowledge of not only the tool but your business process? Have they been "on your side of the table"? Have they been an HR manager or comptroller or auditor or finance officer and done the tasks that their tool addresses? Contact numerous clients that are currently using their product. Spot check the specific features you are counting on using to see if the reference is using them. We have seen vendors provide references that did not even use the product being evaluated! If the vendor can not provide an extensive list of clients who use the product, or they do not have extensive experience solving your exact issue, determine whether your organization is prepared to be a guinea pig. We have seen numerous organizations stuck in limbo for years while their vendor tries to build what was promised. Go back to the expensive vendor(s) and ask why they are so expensive. Do they charge a premium because of their brand? Did they consider something the others didn't? Was there an error in one of the pricing variables (point 2 above)? Assess the low-cost vendor's stability. One way to do this is to consider their financial health, if possible. If the company is publicly traded, have they ever shown a profit? Do their financial statements look like those of a stable, successful company? If the vendor provides their software as a service (SaaS), there may be other considerations for evaluating performance. You can find some interesting articles on SaaS performance here and here. If the company is not publicly traded, it can be hard to perform this analysis, and you may need to rely more heavily on steps 1–6 above. It's a good idea to follow these steps even when there is no major pricing disparity. They become absolutely essential when you're presented with what seems like a sweetheart deal, and you want to avoid the cheap solution trap. © 2026 FH Black Inc. All rights reserved. Content may not be reproduced, excerpted, distributed, or transmitted without prior written consent.
During selection of a new IT system beware of defaulting to the low-cost solution. 7 easy steps steer you away from project failure.
READ MORE
How to Improve IT Project Success with One Calculation
- Jamie Black
- Efficient, Effective and Reliable
- minute(s)Information Technology projects can be the most complex and high-profile you will encounter as a finance team member. Perhaps you have read about the trouble with the Phoenix payroll system implemented by the Canadian public service. Or maybe you have direct experience with severely compromised IT investments at your place of work. There is no shortage of such examples. So, what can finance do to help? In October of 2016, the Auditor General of British Columbia made some suggestions in their report "Getting IT Right: Achieving value from government information technology investments." A 60-Second Overview Regardless of your industry, the report is a valuable read for accountants, and we recommend reading it in full. Here is a quick summary of its major points: IT is important because "every aspect of government depends on IT." Globally, only 29 percent of IT projects are rated "successful." Success is defined as: On Time On Budget Achieving Expected Value Success depends on: People Planning Consultation Governance The report is an absorbing read, but it fails to elaborate on a significant element: What is "value," and how do you calculate it? What about "Value"? The report uses the word "value" 57 times without defining it explicitly. The only comment on how to achieve it is to assess: Alignment of the project with the organization’s specific needs, priorities, and strategies Contribution to the organization’s desired outcomes Cost Level of risk While these are good points, they provide no particular direction to those attempting to assess a project's value or measure the success of a project during or after completion. ROI to Assess Value Before & After Perhaps it's because we believe that numbers are the key to all universal truth (no really, we do), but we argue that finance should calculate proposed and achieved value for IT projects. The accountant in us is very comfortable with Return on Investment (ROI) calculations: This type of calculation should be used to determine optimal use of your organization's investment. But in our experience, these calculations are rarely utilized when considering IT solutions, particularly in the public sector. Why? There are at least two problems with the word "profit" in the context of public sector IT projects. Public sector organizations typically do not think in terms of profit. Even if you work outside the public sector, you may reasonably ask, "How does an ERP system (for example) generate profit for any organization?" "Profit" (and therefore "ROI") may seem like a non-starter. But with a minor change in terminology—replacing "profit" with "calculable benefit"—the concept is applicable to the public sector. The "calculable" part is important; you don't want this exercise to dissolve into imprecise speculation about intangible benefits. Those may also warrant a discussion, but you should not give up the important quantitative analysis. You should focus on those aspects to which you can assign a real dollar value. There are two broad categories of calculable benefits that you should consider: Efficiency of Staff Resources Your staff spends their entire working lives involved with IT systems. A more efficient, convenient, and highly automated solution will help them do their work faster, more reliably, and with less cross-checking and manual review required. If you estimate the hours that a new IT system might save, and multiply it by your staff's hourly cost, you can measure the economic impact of those time savings. Reduction or Avoidance of Direct Expenses There are many direct expenses that a new IT system can help reduce or eliminate. You pay fees to an external accountant—would those fees be reduced if you automated a significant portion of the work they performed? What if your new system could help avoid late payment of invoices and thereby reduce your late fees and penalties to vendors? Perhaps a new system would provide a reduction of ongoing annual maintenance and support costs. An Example Consider a scenario in which your current ERP system is no longer supported. You determine that the risk level of continuing with an unsupported system is unacceptable. You have identified three possible solutions and are working through the selection process. You have seen demonstrations and received fee estimates. You have contacted references and determined each option's strengths and weaknesses. Clearly, there are many considerations (some of which are intangible). But don't underestimate the value of performing an ROI calculation. Calculable Benefit: How much money will we save with each solution? For example, estimate the following separately for each solution: Hours of staff time saved by reduced data processing Hours of staff time saved by automating report creation Estimate avoided late payment fees to vendors due to improved A/P processing abilities Decreased finance costs due to accelerated AR collections Cost: What is the cost of each solution including all features/modules etc. necessary to facilitate the above benefits over a 5 or 10 year period? 3 Advantages of This Approach 1) Forces Detailed Assessment: All too often we see clients who have only a general understanding of how a particular system will help them. Vendors often do little to help, aside from offering marketing double-talk: "Work Smart", "Improve Productivity", or "Improve Efficiency." These aspirational comments are great, but you need measurable results. 2) Easy Comparison of Alternatives: You can immediately begin to see some interesting relationships between the options that were hard to see at first: Solution 3 is four times as expensive as Solution 1, but it provides 4.5 times the value. If all else is equal, and the organization can find the $100,000 budget, Solution 3 is the better choice for your organization. Solution 2, while more expensive than Solution 1, does not provide a commensurate increase in benefit. Thus, if the budget did not allow for $100,000 investment, the next best option is Solution 1. 3) Clear Monitoring of Performance: Another advantage of this approach is that your team has identified very specific, measurable goals to monitor the project and assess success. For example, you estimated a calculable benefit value based on specific time savings in report creation and data entry. These time savings should be measured to determine whether you achieved the benefit. Moreover, if your vendor is confident in their abilities to deliver these time savings, you can attempt to include attainment of the advantages in the contract. "IT-enabled projects aren’t just about technology—they involve substantial changes to an organization’s culture, business processes, and customers. These projects are really IT-enabled business change. A successful project improves services and allows for more effective use of taxpayer money. And their success or failure is about more than just being on time and on budget, it’s also about achieving expected value." –Carol Bellringer, FCPA, FCA Auditor General, British Columbia In sum, ROI calculation is an important tool that allows finance teams to estimate, measure, and demonstrate the value of their IT project. © 2025 FH Black Inc. All rights reserved. Content may not be reproduced, excerpted, distributed, or transmitted without prior written consent.
From replacing your ERP to implementing a new payroll system we illustrate just how powerful ROI is for setting & measuring IT project success.
READ MORE
Is Self-Implementation right for you?
- Jamie Black
- Efficient, Effective and Reliable
- minute(s)For government finance officers looking to make the most of tight budgets, efficiency is key. The RIGHT tools and technology can significantly improve efficiency, provided you can muster the resources to purchase and implement them. Many of our clients are looking to implement technology as inexpensively as possible. Some consider self-implementation. How do you know when this approach is right for your finance, budget, or audit department and when it is a mistake? Here, we'll examine the criteria that determine whether you are likely to succeed in self-implementing a new finance-related system (ERP, payroll, Annual Comprehensive Financial Report (ACFR), financial statement automation, etc.). Over the past 30 years, we have implemented hundreds of technology solutions for clients—ACFR and financial statement automation systems, custom-designed mobile applications, ERP systems, local and wide area networks, servers, and of course, continuous monitoring systems. During the course of these implementations we have tried any number of models: 100% delegation of implementation tasks to client's staff 100% of implementation tasks completed by our team Every task-sharing split in between We have achieved successful outcomes with each of these options. But frankly, we have also had some disappointments. Our wealth of experience has informed the following guidelines for determining the right approach. Self-implementation Requirements: When you engage consultants/vendors to help with implementation, they provide two major benefits: relevant expertise and time to dedicate to the project. As you consider whether your organization can successfully self-implement a particular system, assess your team to determine whether you have the "right stuff" in each of these categories. 1) Expertise: An objective assessment of your team's expertise is critical to ensure you are capable of taking on the implementation yourselves. Technology: The initial configuration of some systems requires considerable technical knowledge, at a level above what's necessary for day-to-day operations. Server setup, database configuration and optimization, and development of custom code for integration with existing tools, are a few common areas of expertise required for initial setup. Do your team members have this expertise already? If not, you should carefully consider whether it is wise to invest your time and money to develop the expertise internally in order to self-implement the project. On the other hand, some systems do not require such sophisticated technological expertise with regard to support systems. Perhaps strong knowledge about that particular application and its day-to-day features is the only requirement for self-implementation. In some cases, an experienced user of Microsoft Windows and Office might have all the technical expertise required for self-implementation. Questions for the software vendor: What technology does your system rely on? Are there servers to set up or databases to administer? Is there any programming or scripting required to implement this system? Specific subject-matter: The level of subject-matter expertise required depends upon the system you are implementing. If you are implementing a new ERP system, are you expert in the functioning of your current system? Have you worked with many different systems? Have you ever been responsible for administering a new ERP system? If you are considering self-implementing a year-end reporting automation tool (ACFR/financial statements), does your team have ample experience preparing those reports today? Do you understand how balances come together and know what G/L accounts should be grouped into each number on your statements? Or perhaps this your first year-end cycle, and you do not have the support of those who prepared prior year reports? Questions for the software vendor: What subject-matter skills do you require of your implementation consultants? What level of experience is essential to lead a successful implementation? When you have seen implementations fail, what skills were implementation team members lacking? Project management: The size and complexity of the project will determine how sophisticated your project management skills will need to be. For example, if the project requires collaboration across a large team, over many months/years, with many individual milestones, lots of complexity, and great risk in the event of failure, you will want a very seasoned, professional project manager. On the other hand, if the project will involve only one or two people, is reasonably straightforward, and you have a great fallback plan in the event of delay or failure, basic project management skills may suffice. At a minimum, we recommend assigning project management duties to someone who exhibits great attention to detail and strong organization and communication skills. For some systems, this approach might be sufficient to guide self-implementation. Questions for the software vendor: How long and complex is a typical implementation project? Do you offer project management services if we decide they're necessary? What guides or checklists can you offer us to assist in managing a self-implementation? 2) Staff Availability: Many organizations pay for professional implementation not because of a lack of expertise, but because they lack available staff time. Being short-staffed or overloaded with work likely means that you will not be able to prioritize required implementation tasks, in which case you will wind up with a system that is never fully/properly implemented. For many systems, considerable time is required to successfully implement the tool. The tasks may or may not be complex from either a technical or subject-matter perspective, but they may take considerable time. You need a clear understanding of how much time is required of your team and how much time your team has available. Consideration should also be given to how frequently you will need to break off from the project to tackle other duties. The more frequent the interruptions, the more difficult it will be maintain momentum, retain instructions, etc. Questions for the software vendor: How much time would you allow for your consultants to implement this system for our organization? How much more time should we allow, given our lower level of experience? Should we multiply the vendor's time estimate by 2? By 3? Measure Your Options As you obtain answers from your vendor, score and plot the responses on a graph like the one pictured here. Projects that fall into the green zone are obvious "self-implementation" candidates. If you plot your project in the yellow or orange zones, the demands of the project are higher and careful consideration of your availability and/or expertise is warranted. Should you determine that the project falls into the "red zone" it usually means that it would be wise to abandon self-implementation and investigate other options. Joint Implementation The choice between self-implementation and fully outsourced implementation is not an all-or-nothing decision. Another option to consider is sharing the workload with the vendor in a joint implementation. You may be able to complete large portions of the work yourselves, yielding significant savings, and make strategic use of the vendor team's expertise and time. Use their team to provide oversight, ballast any expertise weaknesses, or cover any resource availability issues you may experience. By balancing the use of your time, your expertise, and your budget for external services, you can often develop an implementation plan that provides the highest return on your technology investment. © 2025 FH Black Inc. All rights reserved. Content may not be reproduced, excerpted, distributed, or transmitted without prior written consent.
To implement technology as inexpensively as possible many governments consider self-implementation. How do you know if this is right for your organization?
READ MORE
Lipstick on a Pig: 6 Spreadsheet-based Financial Reporting Tool Flaws
- Jamie Black
- Automating Financial Reporting
- minute(s)You may be familiar with the expression "Lipstick on a pig". Variations of the expression date back nearly 130 years but the meaning has not changed; Superficial improvements that do not change the underlying nature of something. Spreadsheets by any other Name We have seen an increasing number of spreadsheet-based reporting automation tools promoted as ultimate solutions for Comprehensive Annual Financial Reports & Budget Books. This is ironic considering many organizations are using spreadsheets today and are looking for a better approach. Sometimes these solutions are desktop add-ons to enable better connections to a source of data. Sometimes these are cloud-based solutions that rely on spreadsheets to maintain their data and develop their reports. Hard to Tell They are Spreadsheets The fact that these are spreadsheet-based tools may be hard to tell on initial review. You can spend hours reviewing their websites and sitting in presentations and still not recognize it. It's not surprising they don't advertise their reliance on spreadsheets given the scientific evidence of their weaknesses and the numerous stories of very public disasters caused by spreadsheets. The Lipstick In fairness, these tools often have improvements over the desktop spreadsheets you are used to, such as: Better collaboration abilities for sharing comments, tracking changes or assigning tasks. Better audit trails and change management. Ability to tie supporting documents to a given value / cell. More granular security / permissions. The Pig But the core of these products are still spreadsheets. That means they suffer from the traditional spreadsheet weaknesses: No database - All data resides in spreadsheets / workbooks not in a database. This means you must build all your own personalized systems to: ensure your G/L balances identify the 100 - 1000 new G/L accounts added each year No processes/workflow - There is no structured system that you can leverage to support industry best practices. What steps should be followed and in what order? You must develop all of these processes on your own and maintain them separately from your reporting environment. No grouping mechanisms - The G/L accounts that sit in your spreadsheet must be summarized in numerous different ways (by object, by fund etc.) to power your Comprehensive Annual Financial Report or Budget Book. If you use spreadsheets, formulas must add the right accounts together. This is fragile and susceptible to error. Moreover, unless you interrogate every formula, there is no way to know what is being included in a given number; there is no legend. Assuming you do get this right in year one, all the new accounts next year means these formulas must all be updated. Tons of custom formulas - All values are derived by "linking" - which is to say writing spreadsheet formulas of varying complexity. Any mistakes you make means errors in your report. Consistency in how these formulas are written or maintained is entirely dependent on the user's expertise, accuracy and completeness. No content libraries - Reporting standards are continually evolving. There are new GASB pronouncements all the time and keeping up with them and what new statements, schedules or footnotes are required this year can be daunting. Spreadsheet solutions do not come with any content. It is entirely up to you to figure out what must be presented and how. No adjusting journal functionality - Adjusting or changing balances is an absolute requirement for financial statement /Comprehensive Annual Financial Report production. In spreadsheets you are left with no tools for the following: The values in your G/L are typically maintained on a modified accrual basis. For many of your statements, you need full accrual. Debit balances in A/P accounts or credits in A/R are just two examples of balances you need to reclassify. Prior year adjustment / restatement caused by changes in accounting policy. Our message in this post is not that the additional features - the "lipstick" - have no value, or that there is no situation when spreadsheets should be used. We are saying that when finance & budget officers evaluate possible solutions for their most complex reporting tasks (Comprehensive Annual Financial Reports & Budget Books), they must exactly match the critical requirements of their processes to the solution's abilities. If they do this carefully, they will find that spreadsheet-based "solutions" are only marginally better than their own collection of desktop-based spreadsheets. © 2025 FH Black Inc. All rights reserved. Content may not be reproduced, excerpted, distributed, or transmitted without prior written consent.
Comprehensive Annual Financial Reporting and Budget Book tools based on spreadsheets are all the rage. Don't overlook their considerable weaknesses.
READ MORE
6 Key Fraud Findings for Government Finance Officers
- Jamie Black
- In Control
- minute(s)Reminders are often critical. I know I have a 9am meeting but without the reminder, I likely would be buried in some other task and miss my conference call. This article provides a quick summary of the recent Association of Certified Fraud Examiners (ACFE) 2018 Report to the Nations on Occupational Fraud and Abuse and acts as a reminder. We should all be reminded how critical strong internal controls are for your organizations success. Further, they form the front line protecting your organization from fraud and abuse. The had several findings that will be very interesting to finance managers in local government. The 2018 report is based on the results of the 2017 survey. As part of the survey, respondents were asked to provide a detailed narrative of the single largest fraud case they had investigated since January 2014. Respondents were then presented with 81 questions to answer regarding the particular details of the case, including information about the perpetrator, the victim organization, and the methods employed, as well as fraud trends in general. While the report is very interesting from many respects, there are 6 points we want to highlight. 6 Findings relevant for Government Finance Officers The most prominent organizational weakness that contributed to the frauds in the study was a lack of internal controls, which was cited in 29.3% of cases, followed by an override of existing internal controls, which contributed to just over 20% of cases. Government and public administration experienced the third highest incidence of losses due to error and fraud, with a median loss of $109,000/ incident. Small organizations had a significantly lower implementation rate of anti-fraud controls compared to large organizations. Small government organizations are more susceptible to fraud. Out of all the government bodies included in the report, from federal to local, small organizations (those with fewer than 100 employees) accounted for the greatest number of fraud occurrences overall. In addition, of the fraud occurrences in small organizations, those involving cash occurred over twice as frequently. The presence of anti-fraud controls was correlated with lower fraud losses. ACFE compared organizations that had specific anti-fraud controls in place against organizations lacking those controls and found that where controls were present, fraud losses were 14.3%–54% lower Anti-fraud controls also correlated with much faster detection. Frauds were detected 33.3%–50% more quickly if the organization used such controls. The report also notes that total losses represented in the study were actually significantly higher. However, to conservatively report loss amounts, the top and bottom 1% of results were excluded from the total loss figure. Even viewing the losses reported through a conservative lens, a typical loss of $108,000 per fraud can be devastating to many organizations, especially when combined with the indirect fallout that often accompanies a fraud scheme. Join us for a free webinar and see how CaseWare's Continuous Controls Monitoring will improve your organization's internal control. We’ll examine the ever-evolving risk profile that governments experience and also demonstrate the significant benefits available (timeliness, accuracy, and cost-effectiveness) of automating monitoring and enforcement of internal control (Continuous Monitoring) using CaseWare solutions. © 2025 FH Black Inc. All rights reserved. Content may not be reproduced, excerpted, distributed, or transmitted without prior written consent.
2018 ACFE Report outlines several key points for government finance officers interested in internal control and eliminating fraud.
READ MORE
Financial Statement Automation Saves Time & Money for Lethbridge
- Jamie Black
- Success Stories
- minute(s)Lethbridge, is a commercial, financial, transportation, and industrial centre with a population of 89,000. The City of Lethbridge provides both essential and nonessential services to its residents, from fire and emergency response to museum and library operations. The City’s Financial Services department is staffed by a team of professionals charged with bringing efficiency, accuracy, and transparency to the organization. CaseWare Working Papers and Financials are the tools the department relies on to fulfill that goal. More and More Spreadsheets As the PSAB (Public Sector Accounting Board) requirements changed, organizations like the City of Lethbridge were forced to change the presentation of their financial statements. Many turned to spreadsheets to accommodate the changes. Municipal governments within the province of Alberta are required to file a Municipal Financial Information Return (MFIR), which must be submitted to the Municipal Affairs office along with audited financial statements by May 1 of each year. At the City of Lethbridge, preparing it involved a multitude of spreadsheets and the dedicated work of one of the City’s most tenured employees. The City of Lethbridge has been using CaseWare Working Papers for many years, although in a limited capacity. “We were just using CaseWare for our balance sheet items,” recalls Tricia Fraser, Financial Reporting Supervisor for the City. “Essentially it was serving as a document holder only. We created our financial statements and other financial reports in Excel®. We needed a better way, as it was just too manual and time consuming.” Embracing Efficiency The City engaged F.H. Black & Company, a CaseWare certified consultant, to help it gain efficiency and reduce manual data entry tasks. “F.H. Black has been a tremendous resource,” says Fraser. “Their knowledge and experience with CaseWare has helped us make more strategic use of the product.” Financial Statements Completed in Record Time Using CaseWare Financials the City tackled financial statement automation. Now the City’s annual financial statement is completed substantially faster than before. “In fact, I had staff asking me what we had forgotten because they were so surprised that we were done so quickly.” That time savings is being put to productive use, Fraser says. “We used to spend so much time preparing documents and assembling the report, that we had little time to analyze the data and look for improvements. CaseWare buys us strategic planning time, time where we can consider what didn’t work, what worked well, and what we can do better. That’s priceless.” Three Weeks Saved in Production of MFIR F.H. Black showed the City how to use CaseWare Working Papers and CaseWare Connector to populate the MFIR report directly. “As a test, we prepared last year’s MFIR both ways, the old way and using CaseWare for the portions we automated,” says Fraser. “Both ways produced the exact same result, only CaseWare did it instantly. Now, instead of handing our auditors a series of spreadsheets and a binder of supporting documentation, we will hand them a CaseWare file.” Fraser says this single change will likely result in lower audit fees, and enables the City to complete its MFIR three weeks sooner than in the past. Improved Accuracy and Security Another benefit the City is realizing through CaseWare is increased accuracy. In the past, personnel would be assigned to troubleshoot and validate the Excel spreadsheets. “Now, when something is out of balance, we can easily follow the trail to the source and make the corrections,” says Fraser. “And because there is no manual input, the opportunity for errors is greatly reduced.” The move to CaseWare Financials has led to improved data security. “I used to be scared to give anyone else access to the spreadsheets, fearing someone would change something and I wouldn’t know who did it or why,” Fraser explains. “In CaseWare, I’m able to set up security so that I can control who has access to what. Now, we have 20 people working in CaseWare, and the data is accessible, auditable, and secure.” Leverage the Investment The City is leveraging its use of CaseWare by using it to produce other financial reports, including sections of its unaudited financial statement that is sent to council prior to the publication of the audited report. “This report is due during our busiest time of the year,” notes Fraser. “We were able to put it into CaseWare and the time savings is unbelievable. Frustration levels of staff during this crunch time are dramatically reduced.” Fraser and her family are relocating soon, and as she discusses new employment opportunities with potential employers, she is certain to ask one question: “I always ask if they use CaseWare. If the answer is no, the conversation is over.” © 2025 FH Black Inc. All rights reserved. Content may not be reproduced, excerpted, distributed, or transmitted without prior written consent.
The City of Lethbridge uses CaseWare Working Papers to automate annual financial statements and the MFIR, driving significant time savings and reducing cost.
READ MORE

