Where Is Your Organization on the Reconciliation Maturity Curve?
- Jamie Black
- Finance Evolved
- minute(s)Where Is Your Organization on the Reconciliation Maturity Curve? A practical self-assessment for finance teams looking to improve productivity & internal controls. Most finance teams can answer whether reconciliations have ever been performed. Far fewer can say, with confidence, whether the process is timely, complete, visible, and strong enough to detect issues before they become control problems. That distinction matters. A reconciliation process may have been performed while still leaving management with limited visibility into overdue accounts, aging reconciling items, recurring discrepancies, review quality, and control effectiveness. A maturity model helps organizations place themselves on the journey from reactive reconciliation to governed, exception-based oversight. The Six Stages of Reconciliation Maturity Stage Core Question Common Symptoms Would we know if a material error, omission, or unreconciled balance existed? Reconciliations have stopped, ownership is unclear, and management has no dependable visibility into errors, unreconciled balances, or accumulating exceptions. Did we reconcile? Manual spreadsheets, inconsistent timing, limited review, high dependency on individual knowledge. Did we reconcile correctly? Standard templates, clear procedures, defined preparer and reviewer roles, but limited automation. Can we reduce manual matching and automate exception management? Automated data imports, automated matching (rules, faster based), exception identification. Do we know what requires attention? Dashboards, aging views, overdue-account reporting, automated escalation, and management visibility. How healthy is our reconciliation process? Continuous monitoring, trend analysis, risk-based frequency, exception ownership, and audit-ready evidence. Stage 1: Uncontrolled Due to staff turnover, conflicting priorities, or other causes, no reconciliations are occurring currently. The risks abound: Undetected errors: Material errors, omissions, or unreconciled balances may exist without management knowing. Financial reporting risk: Inaccurate balances may flow into internal or external reporting before they are identified. Fraud and misuse risk: Unusual or unauthorized transactions may go unnoticed because no regular control is operating. No clear ownership: No one can reliably confirm which accounts should be reconciled, who is responsible, or when the work last occurred. Loss of institutional knowledge: Staff turnover, undocumented routines, or competing priorities can prevent the process from restarting quickly. Unmanaged exceptions: Reconciling items may accumulate without aging discipline, escalation, or resolution. Audit and control failure: The organization may be unable to demonstrate that a key control exists, operated, and was reviewed. Stage 2: Reactive At the reactive stage, the organization is primarily concerned with whether reconciliations are getting done at all. The process may depend heavily on spreadsheets, email, undocumented routines, and the knowledge of a few experienced employees. The risk that reconciliations are not happening at all is reduced. Most other risks remain because the process is still manual, inconsistent, and dependent on individual effort. Stage 3: Disciplined At the disciplined stage, the organization has standardized templates, clearer procedures, documented review steps, and defined ownership. Reconciliations are more consistent and easier to review. This is an important improvement, but it does not automatically solve the visibility problem. A disciplined manual process can still be slow, fragile, and difficult to monitor across many accounts. We have also mitigated the continuity of operations risk somewhat in that procedures are documented, but transition may still be long and difficult. Stage 4: Automated At the automated stage, the organization begins reducing manual matching effort. Bank and general ledger activity can be imported, matching rules can identify routine activity, and exceptions can be surfaced more quickly. This stage is often where tools such as reconciliation automation and integrations with reporting platforms can create significant value. The objective is not simply to make accountants work faster. It is to focus their attention on exceptions, judgment, resolution and the beginnings of management visibility. Here then at stage 3 we have begun to drive significant productivity improvements, focusing our team on the important items and automating the repetitive. The automation also further mitigates the negative impact of losing key staff as the matching rules are a very explicit, formal documentation of how the reconciliation should be performed. Also, the matching can run daily and while not a complete reconciliation it does mean that the reconciliations waiting for the new hire are at least partially completed. Stage 5: Transparent At the transparent stage, management can see what requires attention. Leaders can view completion status, overdue accounts, aging reconciling items, recurring exceptions, and escalation needs without waiting for informal updates. This is the point where reconciliation begins to connect directly with continuous controls monitoring. The process becomes visible enough for management to monitor whether the control is operating, not merely whether staff believe the work is underway. Stage 6: Governed At the governed stage, reconciliation is treated as a management control, not simply an accounting task. The organization monitors process health, evaluates trends, uses risk to determine frequency, assigns ownership for exceptions, and retains audit-ready evidence. The question changes from “Did we reconcile?” to “How healthy is the reconciliation control, and where is risk increasing?” How to Move Up the Curve Progress does not require a single, enterprise-wide transformation. Many organizations begin by identifying high-risk accounts, standardizing procedures, reducing spreadsheet dependency, automating routine matching, and building dashboards that show completion, aging, exceptions, and review status. The organizations that move furthest up the maturity curve are not simply those that match transactions faster. They are the organizations that give management clear, timely confidence that a critical control is operating. As organizations mature, the focus shifts from completing reconciliations to governing the effectiveness of the process itself. The goal is not automation for its own sake. The goal is a reconciliation process that is faster, more resilient, easier to review, and more visible to management. A Useful Self-Assessment A simple way to start is to ask: Do we know every account that should be reconciled? Do we know which reconciliations are late? Do we know how old unresolved items are? Do we know whether exceptions are increasing or decreasing? Would management know if a reconciliation stopped happening? If these questions are difficult to answer, they are a useful starting point for a deeper conversation. F.H. Black works with public sector finance teams to assess reconciliation maturity, identify control gaps, and define a practical path toward more automated, transparent, and governed reconciliation. Contact us to explore a reconciliation maturity assessment for your organization.
Evaluate your reconciliation process with this six-stage maturity model. Identify gaps, improve visibility, and move toward stronger controls and higher productivity.
READ MORE
Reconciliation Delayed Is Risk Multiplied
- Jamie Black
- Finance Evolved
- minute(s)Reconciliation Delayed Is Risk Multiplied A control-risk perspective for finance leaders, treasurers, controllers, and audit committees. Most organizations know they should reconcile their bank accounts. The more important question is whether they are doing it often enough, completely enough, and with enough visibility. For many finance departments, reconciliations remain a manual process performed by a small number of experienced employees on a periodic basis. When workloads increase, vacancies occur, or key staff retire, reconciliations can quickly fall behind. That situation is more than an operational inconvenience. It is a control risk. Why Timing Matters Reconciliations are far more than merely an essential first step in financial reporting. They help identify fraud, bank errors, internal mistakes, and unexpected activity while giving management an accurate view of cash which is critical for accurate cash flow forecasting & investing. The longer the delay in reconciling, the greater the risk to the organization: Errors accumulate, Recovery opportunities diminish, Institutional knowledge fades, and Fraud related losses accumulate (Figure 1) Thus, the value of reconciliation is not simply confirming that most transactions are correct. It is finding the transaction that is not. That is why timing matters. A reconciliation performed weeks or months after the activity occurred may still identify a problem, but the organization may have already lost its best opportunity to correct, recover, or contain the issue. Turnover Is the Risk Nobody Plans For When finance leaders think about risk, they often focus on cyber threats, fraud schemes, or regulatory compliance. Less attention is paid to risk to operational continuity. In many organizations, only one or two employees truly understand the reconciliation process. If one of those individuals leaves, critical controls can stop almost immediately. Reconciliation is too important to reside in the knowledge of a single employee. If a critical control cannot survive the departure or absence of one person, it is not a resilient control. Reconciliation Modernization Solves an Oversight Problem The most overlooked risk may be management visibility. In an environment of manual, decentralized reconciliations most organizations cannot reliably answer basic governance questions: Which account reconciliations are overdue? How old are the exceptions? Are unresolved items increasing or decreasing? Would management know if a reconciliation stopped happening altogether? In that sense, reconciliation modernization is not only about matching transactions faster. It is about giving management timely evidence that a critical control is operating as intended. That ability creates what every CFO, Treasurer, Controller, and Audit Committee needs: confidence that controls are operating, not simply confidence that controls exist. A Practical Path Forward Organizations do not need to transform every reconciliation process at once. A practical starting point is to: Identify high-risk accounts, Increase reconciliation frequency where the risk warrants it, Standardize documentation and review, and Give management visibility into completion status and unresolved exceptions. For organizations already considering account reconciliation modernization, FHB’s broader resources on balance sheet account reconciliations, continuous controls monitoring, Workiva and Adra integration, and public-sector success stories provide useful companion perspectives. The conclusion is straightforward: reconciliation delayed is not risk postponed. It is risk multiplied.
Delayed reconciliations multiply risk. Discover why timing, staff turnover, and poor visibility create control gaps—and how finance leaders can fix them.
READ MORE
How Joint CIO–CFO Leadership Transforms Government Reporting
- Jamie Black
- Finance Evolved
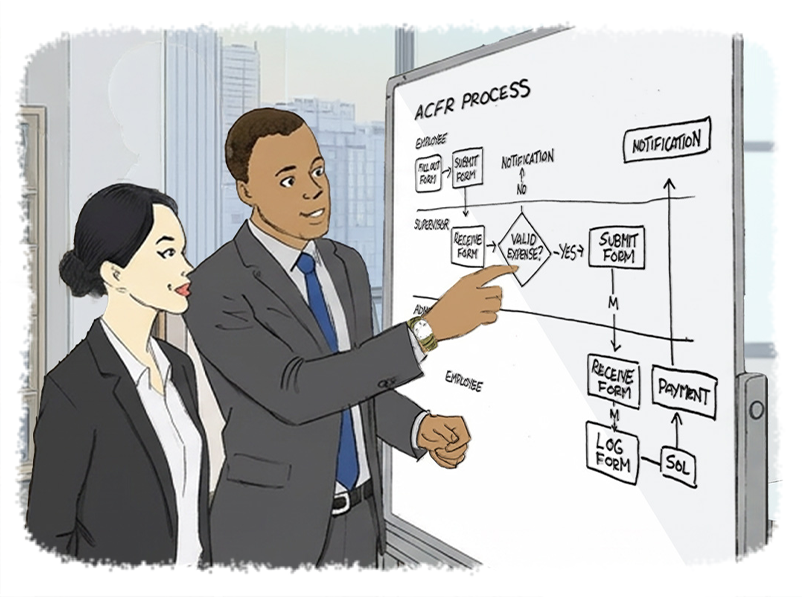
- minute(s)Beyond the Report: How Joint CIO–CFO Leadership Can Transform Government Reporting Productivity and Resilience Across state and local government, core financial and regulatory reporting outputs, such as the Annual Comprehensive Financial Report (ACFR), Schedule of Expenditures of Federal Awards (SEFA), GASB disclosures, and recurring interim financial reporting, remain critical to public accountability. However, the greatest operational risk and opportunity for improvement does not reside in the outputs themselves. It resides in the business processes, controls, and operating models required to produce them. CIOs and CFOs increasingly share accountability for these end-to-end processes. Modern government reporting is not a downstream document-assembly task; it is an enterprise workflow that spans data ingestion, governance, validation, review, audit support, and publication. The strength and efficiency of this workflow directly affect transparency, risk exposure, staff sustainability, and public trust. In California, this challenge intersects directly with the priorities of Envision 2026: California’s Technology Future: Goal 5 (Continually Future-Proof the Business of Government) emphasizes modularity, process consolidation, and emerging-tech readiness, while Goal 4 (Align Strategy Execution Across the State) calls for breaking down silos and improving performance excellence. Goal 2 (Secure California’s Technology Investments) further underscores the need for strong data governance, traceability, and cybersecurity in all enterprise workflows — including financial and regulatory reporting. Core Challenge: The End-to-End Reporting Process Most reporting challenges faced by governments are not driven solely by evolving accounting standards or disclosure requirements. The challenges posed by these changing standards are often exacerbated by fragmented, manual, and loosely governed processes used to assemble recurring reporting outputs. These operating models commonly rely on disconnected spreadsheet-centric calculations, informal review practices, late-cycle validation, and institutional knowledge concentrated among a small number of individuals. These fragmented approaches often result in thousands of hours of unnecessary effort, late nights during reporting season, heavy reliance on a few institutional knowledge holders, elevated risk of errors or control weaknesses during audits, and limited capacity for proactive analysis or strategic initiatives. In such environments, reporting outputs become point-in-time results produced through effort and heroics, rather than predictable outcomes generated by controlled and repeatable processes. What Modernization Really Means Modernizing government reporting is not only about changing report formats or accelerating publication timelines. It is about strengthening the end-to-end reporting solution so that compliant reporting outputs are produced reliably through disciplined execution. A modern reporting operating model emphasizes controlled ingestion of source data, governed transformations and calculations, defined review and approval workflows, continuous validation throughout the reporting cycle, and full traceability from source data through final publication. Add to these benefits a dramatic reduction in the manual effort required each cycle. Organizations that have modernized often report 30–50%+ reductions in preparation time for ACFR and interim reports, fewer last-minute adjustments, and greater staff capacity for value-added work such as forecasting, performance analysis, or process innovation. Standards and Governance Alignment A process-centric reporting solution aligns with GAAP and GASB requirements, GFOA best practices, audit expectations related to documentation, version control, and evidence retention, and enterprise IT governance policies governing access control, security, and data integrity. Perspective from F. H. Black & Company The optimal approach is to address government reporting through the lens of end-to-end business process improvement and automation. Having supported hundreds of public sector organizations in this journey, the focus should not be on the report as a document, but the operational system required to produce reporting outputs consistently, from data sourcing and validation through review, audit support, publication, and roll-forward to future periods. Key to the success of these projects is not merely IT expertise. Improving business processes also requires experience in conducting these processes. That is why all FHB engagements are led by Principal Consultants who are CPAs, with extensive experience working in and with public sector finance, budget, treasury & audit teams. This ensures accounting standards, compliance obligations, and audit expectations are embedded directly into process design while remaining aligned with CIO responsibilities for governance, security, and enterprise resilience. Closing Thought For California CIOs and CFOs, the future of government reporting lies in treating it as a strategic enterprise capability rather than a recurring deadline-driven exercise. When supported by disciplined processes, modern platforms, and close collaboration between finance and technology leadership, organizations can achieve substantial productivity gains, lower operational risk, improve staff sustainability and morale, enhance audit readiness, and ultimately strengthen public trust and accountability. Strong reporting outputs are achieved not by working harder at deadlines, but by building processes and systems that perform reliably year after year. To explore how your organization can modernize its end-to-end reporting processes while aligning with Envision 2026 priorities, contact F. H. Black & Company at www.fhblackinc.com or reach out directly to discuss a no-obligation process assessment.
Discover how joint CIO-CFO leadership can modernize end-to-end government reporting, reduce risk, cut preparation time by 30-50%+, and advance Envision 2026 goals.
READ MORE
Has Artificial Intelligence improved your finance department yet?
- Jamie Black
- Finance Evolved
- minute(s)Finance has always utilized technology. From the humble abacus (2700 - 2300 BCE) to adding machines (1642 CE), to today's PCs. The last 40 years have seen even ‘Moore’ (excuse the pun, couldn’t resist) spectacular technological advancement, as discussed in our Tech for Execs: Ignorance is not bliss article. The questions we tackle here are what will the future bring, how disruptive will this change be for the finance department and what can we do today? Future Technology - Artificial Intelligence (AI) In short, AI refers to a device that perceives its environment and takes actions that maximize its chance of successfully achieving its goals. This definition is intentionally broad as AI could refer to a software application designed to perform bank reconciliations or Terminator robots. When we think about AI in terms of software, one guide is that the application can do things that it was not specifically programmed to do. It learns based on the outcome of previous events. There are two categories of artificial intelligence: 1) Narrow AI Narrow AI is focused on one very specific topic. Still, in its early stages, we can already see developments in narrow AI. AlphaGo Zero is a computer program that taught itself the board game Go by playing against itself. Within days it was better than the best Go-playing applications which themselves beat the best human Go players. Then in 4 hours it taught itself Chess and could beat the best Chess programs in the world (the ones that beat the best humans). Finally, it taught itself Shogi (a Japanese version of Chess played on a bigger board) in 2 hours and was better than the world's best Shogi program. Some other interesting examples: Google's self-taught Go playing AI crushes the best human player, AI in Tesla will predict your destination, MIT's autonomous cheetahs figure out how to navigate obstacles entirely on their own, Boston Dynamics SpotMini locating, recognizing and opening a door, Amazon's use of AI to improve their business processes 2) General AI General AI (sometimes called Artificial General Intelligence or AGI) is a hypothetical machine that exhibits behavior at least as skillful and flexible as humans across a broad set of topics. This is the Hollywood sci-fi that many people immediately think of. Should AGI become a reality, it promises to change every aspect of our world fundamentally. Many experts in the field are in fact worried that it will lead to disaster. To learn more, I recommend an excellent Ted Talk by Sam Harris or Nick Bostram's great book on the topic. AI & the finance department What will AI (narrow or general) mean for the finance department? In the near term, repetitive and time-consuming tasks are being automated at an accelerating pace driving massive improvements in efficiency. These advancements tend to be less risky and relatively low cost and thus are immediately appealing. The benefits are enormous, freeing your team from the mundane, repetitive work allowing them to tackle the difficult, often more rewarding tasks that they may not have time to tackle today. As the technology improves, analyzing data and making decisions based on this analysis are also likely to be automated. We expect that the move to rely on AI for these most complex and difficult tasks - the ones that require years or decades of experience in humans - will be initially slow and cautious. Nearly all studies suggest that the entire finance function (like many others) will be entirely automated by AI exclusively or a human-AI hybrid. The process has begun. Recent research indicates 46% of CFOs in large companies already use narrow AI in some role in their organization and another 30% are investigating its use. Today's Technology - Robotic Process Automation (RPA) For decades finance departments leveraged spreadsheets and more recently databases. These technologies allow for simplistic automation such as calculations or manipulating manually defined groups of data. While basic, this automation has allowed finance departments to complete larger & more complicated tasks with fewer hours of investment. RPA takes automation to the next level and can be considered a pre-cursor to AI. The three characteristics generally associated with RPA: It does not require programming skills on the part of end users, It does not require complex, disruptive integration with existing systems, It is designed to be managed and even implemented by a business user, Some simplistic examples: data analytics & monitoring systems that check thousands of variables in the way it’s been taught, against the benchmarks that have been provided. When exceptions are identified appropriate individuals are notified automatically and escalations occur at pre-determined intervals. automation of reconciliations between any data sources with automated adjustments when common deviations (think bank charges in the context of a bank rec) occur. automated modification of language in your MD&A based on the significance of an identified variance. So if the variance between actual and budget is greater than a predetermined threshold, entire sections of the report turn on and standard analysis is performed, automated analysis of documents to find violations of integrity, automated balancing of amounts across large complex documents. Take advantage now It's clear that technology has, does & will continue to influence the role of finance. While the exact timeline may be difficult to predict, the importance of continuously evaluating and embracing technology is indisputable. It is likely that many of the tools you use today include RPA functionality that is not being utilized. Further, you can expect to see a lot of narrow AI tools specifically targeted at finance in the very near future. Spending a bit of time to leverage these tools can provide your finance department with significant benefits at a very low cost. © 2025 FH Black Inc. All rights reserved. Content may not be reproduced, excerpted, distributed, or transmitted without prior written consent.
AI is coming and it will dramatically improve your finance department's efficiency. It is already starting and many of us don't know it yet.
READ MORE
Is your finance department prepared for these 5 colossal changes?
- Jamie Black
- Finance Evolved
- minute(s)Perhaps the biggest failure of corporate governance today is its emphasis on short-term performance. Corporate Governance 2.0 - Harvard Business Review You may not realize it yet, but your organization is in the early stages of being hit by massive, interconnected and occasionally opposing global changes. These changes are likely not going to reach full strength for 10 or 20 years. None the less, it will take time, planning, and some hard work to get prepared. If these changes turn out to be as big as predicted, being ready may mean the difference between an organization that prospers and one that perishes. In our blog series "Finance Evolved", we consider major trends & forces and how they may affect the finance department to aid in your planning & preparation. Here are the big 5 looming trends: 1) Demographics The population of North America is aging in a way not seen before. This will cause havoc for businesses, governments and the economy generally. 2) Skills Recent surveys reveal gaps between the finance skills required by organizations and those possessed by entry-level management accounting and finance professionals. As the pace of change increases, the successful individual finance professional and the successful finance department will need perpetual skills development. 3) Productivity Despite technological improvements, the pace of growth in productivity has been slowing globally since the 90s. This has already impacted wages and may contribute to income/wealth inequalities and job insecurity in the future. 4) Budgets We see increasing levels of pressure for finance to accomplish more, faster with stagnant or decreasing budgets. Given the other big forces in this list, there is every reason to believe that this pressure will intensify. 5) Technology To say we are living in a time of rapid, continuous technological change is a cliche. There are signs that while the current rate of technological improvement may be slowing, the effects may well be poised to more dramatically affect the finance department than ever before. Be ready for the future Train & mentor staff - The difficulty you have today finding qualified, appropriately skilled staff is going to become much worse. Your best bet is to retain and develop your current team. Document & standardize - Expect the loss of a significant percentage of your most experienced, knowledgeable workforce in the next 2 decades. Without excellent organizational supports, this will come with a consequent decline in organizational productivity. Plan ahead - Governments at all levels will see reduced revenue growth and increased expenses, further straining budgets. You can expect reduced governmental services and/or increased taxation. Streamline & automate - Organizations of all types will be under growing pressure to increase productivity. Software and automated systems are your best tool to do more with less. Upgrade your skills - The requirement for greater productivity will mean that your value will be increasingly tied to your ability to lead, to streamline, to automate and to improve. Conversely, if your skills are primarily data entry/bookkeeping, you are likely to be automated into the unemployment line. Do you have the skills to leverage technology to help you address the dramatic staffing, efficiency, and budget challenges we will see in the next 10 to 20 years? Watch for future articles in our Finance Evolved series which will dive deeper into these topics and explore additional strategies designed to aid the transition to world-class finance organization. © 2025 FH Black Inc. All rights reserved. Content may not be reproduced, excerpted, distributed, or transmitted without prior written consent.
To function effectively & efficiently in the coming decades, your finance department must plan for these 5 major changes right now.
READ MORE

